

Last updated 6 November 2026 · Covers 2026/27 and the announced April 2027 changes
Cash ISAs pay tax-free interest, while NS&I Premium Bonds offer tax-free prizes through monthly draws. A fixed Cash ISA gives you a known rate for its term, while easy-access rates can change. Premium Bonds winnings vary, and a typical saver can receive less than the headline prize fund rate.
When my husband and I were saving our £36,000 house deposit on one salary, we each held an ISA in our own name. We also compared higher-paying savings accounts for money we kept outside our ISAs. If you’re choosing where to put your next savings pot, start with what you need the money for and when you’ll need it.
Cash ISA vs Premium Bonds UK at a glance
| What to compare | Cash ISA | NS&I Premium Bonds |
|---|---|---|
| UK tax | Interest is tax-free. | Prizes are tax-free. |
| Minimum | Depends on the provider. Some accounts open from £1. | £25 minimum purchase. |
| Limit | Up to £20,000 in new subscriptions in 2026/27, shared with your other ISAs. | £50,000 total holding per person. |
| Return | Interest at a fixed or variable rate. | Monthly prize draws. You can win nothing. |
| Access | Check transfer times and withdrawal limits. Fixed accounts can charge for early access. | No cash-in penalty. NS&I says withdrawals normally take three to five working days. |
| Protection | Eligible deposits are protected by FSCS up to £120,000 per eligible person per authorised firm. Brands sharing a banking licence share the limit. | Backed by HM Treasury. |
Your ISA limit applies to new payments. A £25,000 Cash ISA balance could come from previous years’ subscriptions or a formal ISA transfer. If you’re moving an existing ISA, ask the receiving provider to arrange the transfer. See ISAs explained and the Cash ISA rules after the Budget.
Why the April 2027 savings tax rise changes the maths
From 6 April 2027, the announced rates on taxable savings interest are 24% at basic rate, 44% at higher rate and 49% at additional rate. The Personal Savings Allowance is £1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and £0 for additional-rate taxpayers. Cash ISA interest and Premium Bonds prizes sit outside that calculation.
Suppose a savings account pays £470 in interest and you’ve already used your full allowance. At the announced 44% rate, you’d keep £263.20, assuming all of that interest falls in the higher-rate band. If you earned the same interest inside a Cash ISA, you’d keep £470.
If your ordinary savings interest is already covered by your allowances, compare the rates and withdrawal terms across all accounts. A taxable account paying more can leave you better off in that situation. My Savings Tax Rise 2027 guide shows how much cash can be covered at different rates.
What average luck looks like on £10,000 and £25,000
The prize fund rate describes prizes across all eligible Bonds. A few very large prizes pull up the average. The median is the middle result in the model, which gives you another way to compare it with interest you can budget for.
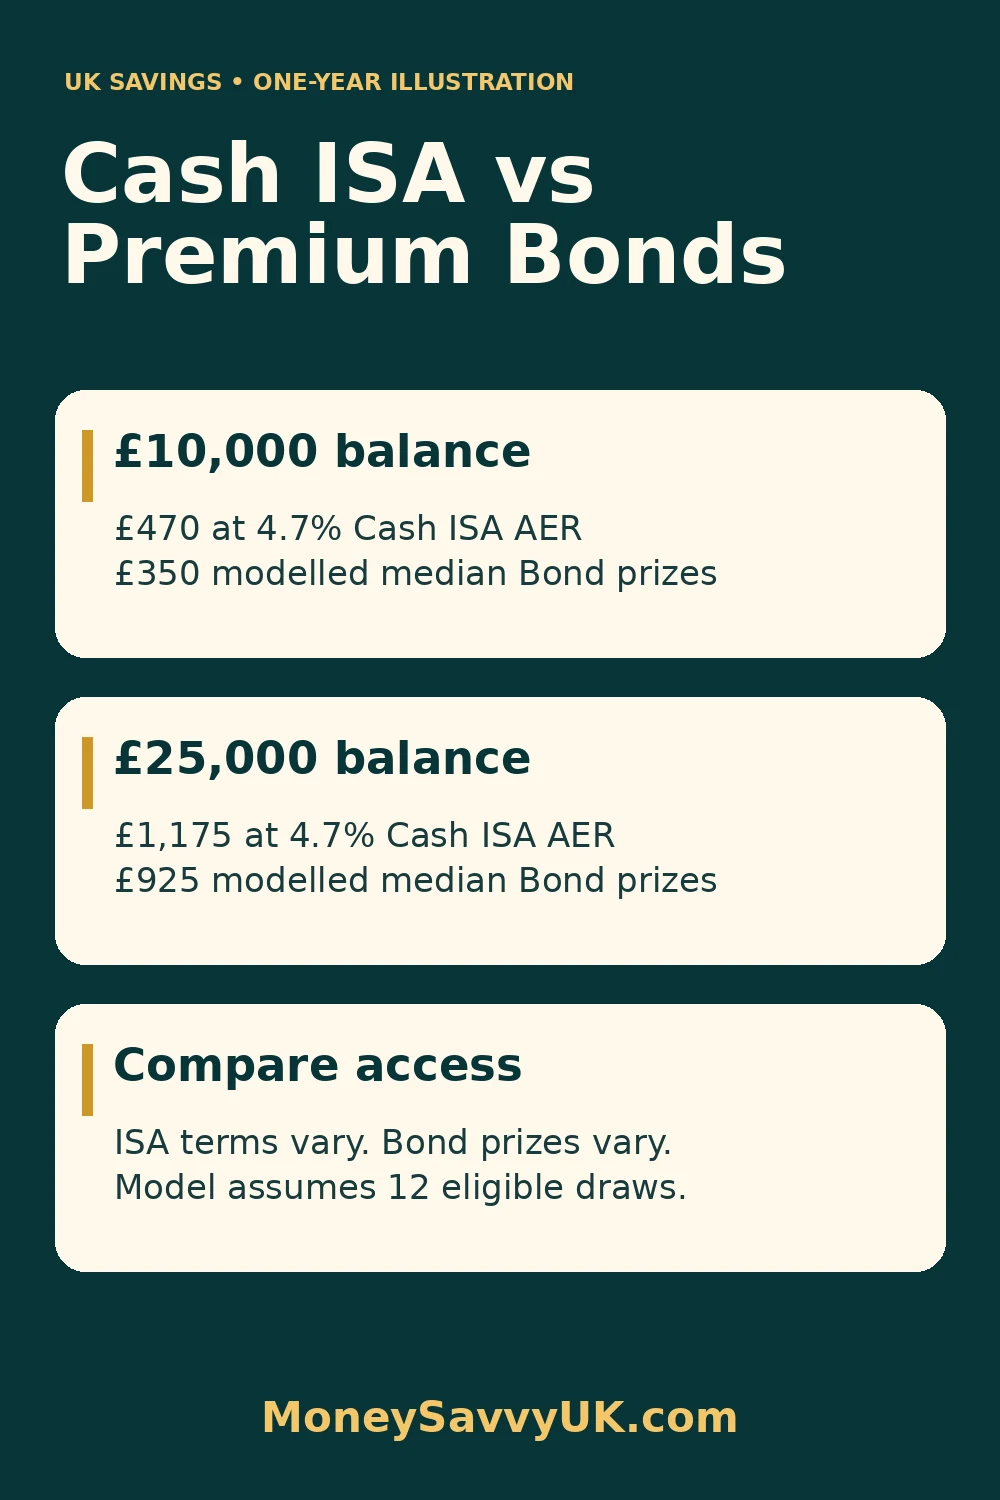
| Balance | Illustrative fixed Cash ISA at 4.7% AER | Estimated median Premium Bonds prizes |
|---|---|---|
| £10,000 | £470 | £350 |
| £25,000 | £1,175 | £925 |
The ISA column assumes the balance earns 4.7% for a full year. This is an illustrative rate. The prize figures use a compound Poisson approximation based on NS&I’s November 2026 prize breakdown and published odds of 21,000 to one per £1 Bond per draw, held constant over 12 eligible draws. Actual odds, the prize mix and your winnings can change.
At these balances, a completely blank year is uncommon in the model. Smaller holdings have a higher chance of winning nothing. New Bonds also need to be held for a full calendar month before entering a draw, so 12 eligible draws can take longer than 12 months from purchase.
Use the Cash ISA vs Premium Bonds Calculator to compare your own balance and interest rate. Check its assumptions before comparing the output with the median figures above.
When each option might fit your savings plan
1. Check whether you need predictable interest
If you have ISA room and want a predictable return, compare fixed Cash ISAs for money you can leave untouched. If you might need the money sooner, compare easy-access Cash ISAs and check how quickly withdrawals reach your bank. A variable rate can fall.
2. Decide how much uncertainty you can live with
Premium Bonds can be worth comparing if you’ve used your ISA allowance, pay tax on ordinary savings interest and can accept uneven returns. You can cash them in without a penalty, but allow time for the money to reach your bank. For cash you might need today, check the Emergency Fund Calculator and keep the immediate portion somewhere you can reach it.
3. Give each savings pot a job
You can use both. Someone saving for a house deposit might keep the money they need on a fixed date in accounts with predictable interest, and use Premium Bonds for a separate pot where prizes are a bonus. My house deposit guide shows how to work backwards from a buying date.
For longer-term money you’re considering investing, see my Vanguard vs Trading 212 ISA comparison. Those are investment accounts, and the value of investments can fall. My free 7-Day Financial Reset Kit and Sinking Funds & Savings Pots planner can help you organise pots by goal.
What I’d do first
I’d write down when I need the money, how much ISA room I have left, and how much interest I expect across all my taxable accounts. Then I’d compare the interest I could keep with a realistic range of prize outcomes. If the plan only works when I win a prize, I’d change the plan.
Cash ISA vs Premium Bonds UK: key takeaways
- Cash ISAs pay tax-free interest. Premium Bonds offer tax-free prizes.
- Compare the return you could keep after tax once you’ve checked your allowances.
- Choose access that matches when you’ll need the money.
- Use the prize estimate as an illustration and budget for the possibility of less.
Cash ISA vs Premium Bonds FAQs
Are Premium Bonds better than a Cash ISA?
A Cash ISA can suit money where predictable interest matters, while Premium Bonds suit savers comfortable with uncertain prizes. Compare the interest you could earn, your available ISA room and how quickly you’ll need the money.
Can I hold Premium Bonds and a Cash ISA at the same time?
Yes, you can hold both. Buying Premium Bonds does not use your annual ISA subscription allowance.
Do Premium Bonds count towards the Personal Savings Allowance?
No, Premium Bonds prizes are tax-free. Cash ISA interest also sits outside the Personal Savings Allowance calculation.
Sources
- NS&I Premium Bonds terms and November prize allocation
- GOV.UK ISA guidance and MoneyHelper Cash ISA guidance
- HMRC savings allowances and Autumn Budget 2026
- FSCS deposit protection
I’m not a financial adviser. This guide shares my experience and general information and does not constitute regulated financial advice.